


 Raamatupoed


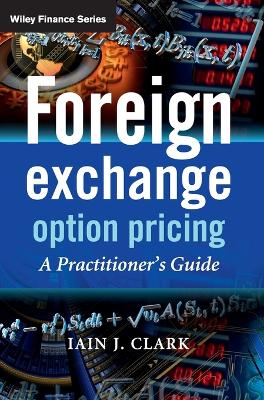

Foreign Exchange Option Pricing – A Practitioner′s Guide
138,75 €
This book covers foreign exchange options from the point of view of the finance practitioner. It contains everything a quant or trader working in a bank or hedge fund would need to know about the mathematics of foreign exchange—not just the theoretical mathematics covered in other books but also comprehensive coverage of implementation, pricing and calibration. With content developed with input from traders and with examples using real-world data, this book introduces many of the more commonly requested products from FX options trading desks, together with the models that capture the risk characteristics necessary to price these products accurately. Crucially, this book describes the numerical methods required for calibration of these models – an area often neglected in the literature, which is nevertheless of paramount importance in practice. Thorough treatment is given in one unified text to the following features: Correct market conventions for FX volatility surface constructionAdjustment for settlement and delayed delivery of optionsPricing of vanillas and barrier options under the volatility smileBarrier bending for limiting barrier discontinuity risk near expiryIndustry strength partial differential equations in one and several spatial variables using finite differences on nonuniform gridsFourier transform methods for pricing European options using characteristic functionsStochastic and local volatility models, and a mixed stochastic/local volatility modelThree-factor long-dated FX modelNumerical calibration techniques for all the models in this workThe augmented state variable approach for pricing strongly path-dependent options using either partial differential equations or Monte Carlo simulation Connecting mathematically rigorous theory with practice, this is the essential guide to foreign exchange options in the context of the real financial marketplace.

Detailid

176 x 253 x 23 mm
 Võrdle suurust
Raamatu suurus

Arvutus põhineb keskmisel lugemiskiirusel, kus 200-250 sõna lugemiseks kulub 2 minutit.
 Eesti suurim raamatumüüja
 Eripakkumised püsiklientidele
 Tasuta tarne tellimustele üle 39 €
 Kiireim tarne alates 2 tunnist
Copyright © 2026 www.rahvaraamat.ee. Kõik õigused kaitstud.
Rahva Raamat AS, 10421903, Telliskivi 60/2 (I-hoone), Tallinn, 15073, Eesti